


Law No. 15270 of 2025 was passed in November, alongside the reformed 2026 ITCMD on donations and inheritances and the Consumption Tax Reform, and introduced two new provisions that affect the lives of those with financial ties to more than one country: the 10% withholding tax (IRRF) on dividends and the Minimum Individual Income Tax (IRPF Mínimo) on annual income exceeding R$ 600,000.
The first tax return that will reflect all of this is the 2027 return, covering income from 2026. However, Law 15.270/2025 includes foreign income—even under a tax treaty—in the calculation basis for the Minimum Income Tax. Many people with international tax situations have not yet realized that the Minimum Income Tax, as currently written, also applies to income that Brazil has agreed by treaty not to tax. This text is relevant to those who:
- lives in Brazil and receives income from abroad (pension, rent, dividends, interest, salary);
- lives abroad, has not formally completed the process of permanently leaving the country, and still receives income in Brazil—from rent, dividends, and stock market transactions;
- is in the process of moving—has just left, is returning, or has spent most of the year on the move;
- wants to understand the extent to which a double taxation agreement will actually provide protection in 2026, before the first tax return includes the new minimum income tax.
Double taxation agreements (DTAs) are international treaties that Brazil has signed and ratified with 37 countries. For each type of income, a DTA determines which of the two states may levy tax, or how the two may share the tax revenue between them. When a Brazilian law attempts to tax income that the treaty has attributed to the other state, Article 98 of the National Tax Code (CTN) comes into play: “International treaties and conventions revoke or modify domestic tax legislation and shall be observed by any subsequent legislation.“
That is the point of this article. I will use an illustration by the greatest international tax expert of the 20th century—the German Klaus Vogel—and apply it to two fictional characters: Joana, a resident of São Paulo who receives dividends from a Spanish company, and André, a Brazilian airline captain living in Rome with stock market investments in Brazil. The risk both face in 2026 is the same: the IRS including treaty-protected income in the Minimum Income Tax base. And the defense argument is the same, though each has its own flavor.
Law 15270/2025 at a glance: what changes for those with “high incomes” abroad
The law has three main provisions. The first extends the personal income tax exemption up to R$ 5,000 per month, and this was the aspect that dominated the attention of the media and politicians. I won’t comment on that here. The other two points relevant to this text are:
- A 10% withholding tax on dividends. Starting in 2026, profits and dividends paid by the same legal entity in Brazil to the same resident individual in excess of R$ 50,000 per month are subject to a 10% withholding tax1See Law No. 9,249/1995, Art. 6-A, as amended by Law No. 15270/2025.. For non-residents, there is no minimum threshold; any dividend remitted abroad is subject to a 10% withholding tax.
- Minimum Personal Income Tax — This is a minimum tax threshold: it ensures that individuals with significant annual income pay at least a minimum percentage on their total income, including all sources—taxable income, income subject to withholding tax, and exempt income. For annual incomes equal to or greater than R$ 1.2 million, the tax rate is 10%; between R$ 600,000 and R$ 1.2 million, there is a linear tax bracket2See Law No. 9,249/1995, Art. 16-A, also included in Law No. 15270/2025..
Layer |
Who is affected |
Tax rate |
Home |
Nature |
|---|---|---|---|---|
Withholding tax on dividends (Section 6-A) |
A resident who earns more than R$ 50,000 per month from a single source, or any non-resident |
10% |
Amount distributed |
Advance payment (resident) / final payment (non-resident) |
Minimum Personal Income Tax (Art. 16-A) |
Resident with an annual income of more than R$ 600,000 |
Up to 10% (flat rate between R$ 600,000 and R$ 1.2 million; 10% above that amount) |
Total income—including exempt and exclusive income |
Annual tax return; Withholding tax for the year is offset |
The Minimum Income Tax is calculated annually. In 2027, on the 2026 tax return, every resident with “high” income will see the new tax applied for the first time. The law was passed at the last minute: anyone with accumulated profits through 2025 had to approve the distribution via board resolution by December 31, 2025, to take advantage of the transitional exemption (payment through 2028 without withholding tax or the Minimum IRPF). Those who missed the deadline lost the opportunity.
The focus of this article is the design of the Minimum Income Tax (IRPF Mínimo): its tax base includes all income, including exempt income and income subject to exclusive withholding tax. A tax with such a broad scope must, in practice, exclude from the tax base anything that Brazilian law lacks the authority to tax—in this case, whenever Brazil has signed a treaty waiving its power to tax that income in favor of the other state.
But that is not what happened, as we have described regarding how Bill 1,087/2025 eventually became Law 15270.
Law 15270 in Joana’s case: a resident of Brazil receiving dividends from a Spanish company; foreign income exempt under a tax treaty
Joana is 47 years old, has lived in an apartment in Pinheiros since her teens, and has been a managing partner of a small technology company based in Madrid since 2018, after spending a few years abroad and returning. She remained a partner and, since then, has received approximately €120,000 annually in dividends from the Spanish company. In addition, she is a partner in a Brazilian fashion consulting firm, from which she receives approximately R$800,000 per year in dividends. Joana is, without a doubt, a tax resident of Brazil: she lives here, works here, and has a family here. There is no dual residency.
The situation through 2025
Brazilian dividends were exempt under Law No. 9,249/1995 (Art. 10). Spanish dividends were taxed in Spain—the company had already been taxed under the Impuesto sobre Sociedades (IS), and the distribution was subject to Spanish withholding tax. In Brazil, Joana reported them as exempt income, paying nothing. The basis for this was not Brazilian domestic law, but rather Decree No. 76,975/1976, which enacted the Brazil-Spain Convention for the Avoidance of Double Taxation (signed in 1974, in force since 1975). Article 23(4) of the treaty contains an express exemption clause for dividends: when Spain may tax them under the convention, Brazil exempts them from the Brazilian resident’s income tax calculation.
An important detail about how DTAs work
It is worth noting here that double taxation treaties may provide for two different mechanisms for the elimination of double taxation:
- the offsetting of income tax paid in one country against tax payable in the other (credit method); or
- the exemption from income tax on foreign income (exemption method).
Brazilian DTA agreements almost always use the credit method, but Spanish dividends are a notable exception, as Brazil has agreed to apply the exemption method.
Law 15270/2025 simply ignores the fact that both mechanisms exist, and that Brazilian DTAs use both. Only the credit method is addressed for calculating foreign income in the tax base for the Minimum Personal Income Tax3Law 15270/2025 makes no direct reference to the offset of tax paid abroad, but to Article 12 of Law 9,250/1995, which states in subsection VI that the annual income tax due at progressive rates may be reduced by offsetting tax paid abroad, provided there is reciprocal treatment (the procedure in the absence of a treaty). It also refers to Law No. 14,754/2023, which addresses the offset of tax credits when there is a double taxation agreement (DTA) or, in its absence, reciprocal treatment. Since domestic law does not address exemptions, but Law 15270/2025 explicitly states that exempt income is included in the calculation basis for the Minimum Personal Income Tax (IRPF Mínimo), this gap remains..
The situation in 2026
The numbers have changed, but the treaty hasn’t. In 2026:
- Brazilian dividends (R$ 800,000/year, ~R$ 66,600/month per source): exceed the monthly limit of R$ 50,000, and are therefore subject to a 10% withholding tax. They are also included in the personal income tax base.
- Spanish dividends (€120,000, ~R$700,000/year at the current exchange rate): remain exempt in Brazil pursuant to Article 23(4) of the Brazil-Spain Double Taxation Treaty. The treaty has not been terminated, amended, or superseded. Law 15270/2025 does not affect it.
The sum of these two income streams brings Joana’s annual income to approximately R$ 1.5 million, which exceeds the threshold for the 10% bracket of the minimum income tax (IRPF Mínimo). And here lies the problem: since the Minimum Income Tax is calculated on all income, including exempt income, a literal reading of the law would include the R$700,000 from Spain in the tax base for the Brazilian minimum tax.
If that happens, Joana will have paid Brazilian taxes on income that Brazil agreed in 1974 not to tax. It is backdoor double taxation—a form of taxation that ordinary law cannot impose without violating the treaty and Article 98 of the CTN.
The legally defensible answer is straightforward: Joana’s Spanish dividends should not be included in the base for her Minimum Income Tax. The Minimum Income Tax is clearly a form of income tax, and Brazil’s authority to tax income originating abroad is precisely what the DTA limits. This is not a matter of invoking an exemption; it is a matter of recognizing that, in the provision of Article 23(4) of the treaty, Brazil waived the taxing authority it normally possesses, creating an area of non-taxation. A subsequent ordinary law does not restore that authority.
Until the IRS issues regulations on the matter (we have not yet found any official guidelines regarding the IRPFM), and the first 2027 tax return is issued, Joana needs three things: robust documentation of the Spanish dividend regime, a calculation of the Minimum IRPF in two versions (with and without foreign dividends), and a willingness, if necessary, to argue administratively or in court for the exclusion of this income from the tax base. Because it is almost certain that the software generating the 2027 income tax return will not be adapted to Joana’s hypothetical situation.
André: a Brazilian driver in Italy who invests in the Brazilian stock market
André is a Boeing 787 captain for an Italian airline headquartered in Rome. He lived in Brazil until 2022, when he accepted the job and moved there with his wife and two children. They bought a house in Trastevere; the children attend an Italian school, and his wife took a job at a European NGO. The family lives in Italy.
However, André hasn’t officially left Brazil for good. The reason was practical: he still owns an apartment here in Belo Horizonte that he inherited from his mother, a stock portfolio on B3 built up over 20 years, and some fixed-income securities. He feared his financial investments would become irregular due to poor regulations governing stock market investments, and for that reason, he continued to file his income tax return as a tax resident in Brazil as well.
The crux of the matter: dual tax residency vs. Law 15270
Under the regulations (SRF Normative Instruction No. 208/2002), André is still a tax resident in Brazil: he has not left the country permanently, nor has he been absent for more than 12 consecutive months without notifying the authorities. Under Italian law, he is a tax resident in Italy, as he remains there for most of the tax year, with residence or domicile within the territory of that State4The concept of tax residence under Italian law is set forth in CIR/85, Art. 2, and the Testo Unico.. Both Brazil and Italy claim him as a resident—the classic scenario of dual tax residency—and how the agreements resolve the tiebreaker.
That is the purpose of Article 4 of the DTA. The Brazil-Italy Agreement has been in force since 1981 (Decree No. 85,985/1981). Article 4 provides, as tie-breaking rules, a series of tests that determine, for the purposes of the treaty, in which of the two States the person is a tax resident. The sequence is: 1. permanent residence; 2. center of vital interests; 3. habitual residence; 4. nationality; and, as a last resort, 5. mutual agreement between the competent authorities.
In André’s case, the first test is decisive: his permanent residence is in Italy (the house in Trastevere). The apartment in Belo Horizonte is rented out. Center of vital interests? Also Italy—work, family, school, social life. Based on the DTA, therefore, we can conclude that André should be considered a tax resident of Italy for the purposes of applying the benefits of that treaty.
What does that mean in 2026?
It is fair to say that, under the treaty’s tie-breaker rule, being a tax resident in Italy has two consequences in André’s case.
First—income earned abroad (pilot’s salary). Article 15 of the Brazil-Italy Double Taxation Agreement addresses employment income: the salary paid to the captain of an aircraft engaged in international traffic is taxable only in the State of Residence (Italy, by tiebreaker), so Brazil should not tax this income. This is reinforced by Article 15(4), which grants the State where the airline has its place of effective management (also Italy) the authority to tax.
Based on the Brazil-Italy Double Taxation Agreement, we can conclude that Brazil cannot tax this salary, neither under the progressive income tax (carnê leão) nor under the minimum income tax. André earns about €180,000 per year (approximately R$1 million)—income over which Brazil relinquished its taxing rights 45 years ago.
Second—Brazilian income. Trading in shares on B3, rent from the apartment in Belo Horizonte, and interest from fixed-income investments total approximately R$450,000 per year. Since these income streams originate in Brazil, Brazil may tax them, subject to the specific rules of the Double Taxation Agreement (rental income under Art. 6; dividends and interest under Arts. 10 and 11, respectively, with a 15% limit; stock market gains under Art. 13). In Italy, Italian income tax will be due, but the tax paid in Brazil may be used as a credit, with a presumed credit of 25% for dividends and interest (Art. 23).
The real risk in 2026
Regardless of the international treaty, since the Brazilian Internal Revenue Service sees André’s CPF marked as a tax resident in Brazil, it must require a full tax return, including his Italian salary. The math is simple: Brazilian income (R$ 450,000) + Italian salary (~R$ 1 million) = ~R$ 1.45 million/year → above R$ 1.2 million → minimum IRPF of 10% → minimum tax of approximately R$ 145,000.
The fact that André has documentation from DTA Brazil-Italy to report his Italian salary as exempt/non-taxable income is of little help in this calculation, since Law 15.270/2025 does not provide for this situation. It is not an exemption under Brazilian law, but rather income that Brazil should not be able to tax. Including it in the Minimum IRPF base amounts to levying a tax outside the self-limitation that Brazil agreed upon with Italy. The answer, just as it was for Joana, lies in Article 98 of the CTN: the Brazil-Italy Double Taxation Agreement must be observed even if the Minimum IRPF is provided for in a subsequent law. Following this reasoning, the pilot’s salary should not be included in the tax base, despite the lack of provision in domestic law to that effect.
André’s case teaches readers in similar situations two things. First, yes, the DTA does apply, and the tiebreaker should protect him. Second, this protection may need to be asserted in a dispute with the IRS (either administratively or in court). In practice, the best solution for most “Andrés” is to formalize their permanent departure or waive the treaty benefit and seek to offset the Italian tax as a credit, depending on what the numbers suggest.
The Vogel Mask: Why the Treaty Prohibits the Minimum Income Tax Under Law 15270
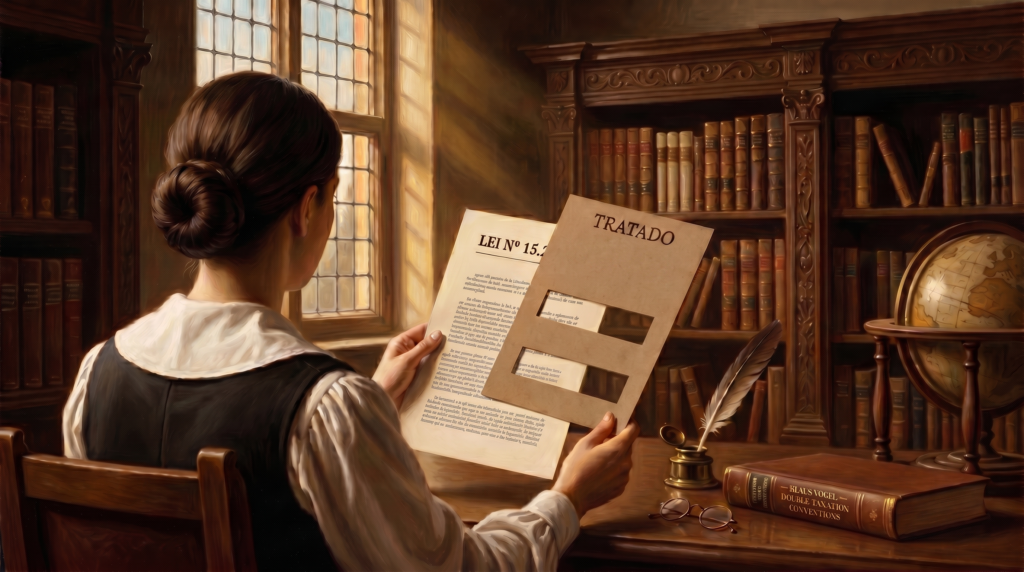
At this point, it is worth pausing to consider: on what grounds can one claim that a new Brazilian law can tax income that an old treaty stipulated Brazil cannot tax? The best answer comes from an analogy that the German legal scholar Klaus Vogel (1930–2007) contributed to the literature on international taxation.
Vogel was a professor at the University of Munich and is considered the foremost international tax expert of the 20th century. His article-by-article commentary on the OECD Model Convention (Klaus Vogel on Double Taxation Conventions) is the global standard on tax treaties. Among his technical and conceptual contributions, Vogel offered a metaphor to explain to a layperson how a treaty and domestic law relate to one another.
The metaphor of the cut-out cardboard mask
Imagine a cut-out cardboard stencil—the kind made of brown kraft paper, with cutouts that reveal a secret message underneath. Hold this stencil over the text of Brazil’s tax law. Three things happen:
- Where the treaty takes precedence—the “mask”—it specifically addresses the matter. Domestic law cannot be applied in such cases, because the treaty provides otherwise.
- The treaty makes no mention of these exceptions—the “windows.” Domestic law continues to apply as usual. This is an area where Brazil exercises its tax jurisdiction without interference.
- If someone tears off the mask—whether the treaty is denounced, unilaterally revoked, or ceases to exist—domestic law remains intact. It was never revoked. Its application was merely suspended in those areas.
This metaphor conveys three ideas at once that always confuse those just starting out in my field:
- The treaty does not create a tax. No bilateral tax treaty imposes any tax. Taxes are always established by a state’s domestic law. The treaty merely limits domestic jurisdiction.
- The treaty does not repeal or amend domestic law. The law remains in force. If the treaty is terminated, Brazil continues to apply its law without needing to enact any new legislation.
- A subsequent domestic law does not remove the mask. Even a law enacted in 2025 encounters a mask from 1974 (Spain) or 1978 (Italy) that is already superimposed on the legal text, and Article 98 of the CTN prevents this new law from removing the mask.
Applying this to our characters
Joana looks at Article 16-A of Law 15.270/2025, which states that all income is included in the minimum income tax base. Overlaid on this text is a mask with the exact text of Article 23(4) of the Brazil-Spain Double Taxation Agreement. The cutout covers the case of Spanish dividends, preventing the Minimum Income Tax under Law 15.270/2025 from applying. The new law remains visible in the window—for Brazilian dividends, stock market gains, and property rentals in São Paulo. But when it comes to Spanish dividends, the Minimum Income Tax is blocked by the cardboard.
André looks at the same text and sees another “mask”—that of the Brazil-Italy Double Taxation Agreement (DTA). The provision in Article 4 (tie-breaking rule) covers everything: since he is a tax resident of Italy for the purposes of the treaty, the mask covers all income that the treaty attributes exclusively to Italy. The provision in Article 15 specifically covers André’s salary as a pilot. Brazilian law remains applicable to the rent from the apartment in Belo Horizonte (Article 6 of the DTA, taxation of real estate in the country where the property is located) and to dividends and interest from fixed-income investments (Articles 10 and 11, but with a 15% cap). But what about his Italian salary? Blank.
Schoueri’s remark
Professor Luís Eduardo Schoueri, in tribute to Vogel, makes an important point. Viewing the treaty merely as lex specialis in relation to domestic law—a special law in relation to general law—opens up conceptual space for someone to argue that an even more specific domestic law would prevail over the treaty. It would be a disguised treaty override. Schoueri proposes viewing the treaty and domestic law as occupying distinct levels: the treaty is not on the same shelf as domestic law; it stands above it, limiting the State’s authority to tax. This closes the door to any argument that the IRPFM, being new and specific, could derogate from the treaty.
This nuance is relevant to our article because it reinforces the practical conclusion: Law 15270 of 2025, which imposes the Minimum Income Tax, is ordinary domestic law. If the treaty states that the authority to levy the Minimum Income Tax does not exist for a particular type of income, then the Minimum Income Tax does not apply to that income either. The treaty takes precedence. And it operates at a different level.
Article 98 of the CTN: yet another reason why Law 15270 does not take precedence over an international treaty
In addition to the international aspect, Article 98 of the National Tax Code also states the following:
International treaties and conventions supersede or amend domestic tax laws and shall be observed by any subsequent legislation.
Although it is not entirely accurate to say, based on the comments by Klaus Vogel and Schoueri, that treaties “repeal or amend” domestic law, the relevant part here is the second one—“they shall be observed by any subsequent law.” Brazilian domestic law itself states that any law enacted after the DTA must comply with it.
Law 15.270/2025, if applied without proper interpretation, would include treaty-protected income in the minimum income tax base. The diligent taxpayer—Joana, André—has three possible options:
- Report this income as part of the taxable base and pay the tax, then file for a refund. This approach offers greater protection against tax assessments, but it negatively impacts cash flow and may require legal action (such as a declaratory action asserting the absence of a legal tax relationship).
- Exclude this income from the taxable base pursuant to Article 98 of the CTN. While legally defensible, this requires solid documentation and may trigger an audit. In addition, the income tax return software may not allow you to report the income without including it in the minimum income tax base.
- Pre-emptive writ of mandamus prior to the 2027 tax return. It brings the matter forward and may protect against the imposition of heavier fines in the event of a tax assessment.
The choice depends on the risk profile and the amount involved. The argument is not unusual: the STJ has already applied Article 98 of the CTN in similar cases—for example, in the taxation of profits from foreign subsidiaries (Article 74 of Provisional Measure 2,158-35, later replaced by Law 12,973/2014), when the DTA attributed jurisdiction solely to the other state. But it entails risking a potential dispute with the tax authorities, especially when the matter involves a more in-depth analysis of the facts (as in André’s case).
Looking at the map of Brazilian DTAs
Brazil has approximately 37 tax treaties in force. For the purposes of this discussion, it is worth highlighting those most relevant to Brazilian expatriates or residents with foreign income:
Country |
Reference |
General method for eliminating double taxation (on the Brazilian side) |
|---|---|---|
Credit (Art. 23) |
||
Spain |
Tax credit + specific exemption for dividends (Art. 23(4)) |
|
Italy |
Credit (Art. 23) |
|
France |
Credit (Art. XXII) |
|
Netherlands |
Credit (Art. 23) |
|
Japan |
Credit (Art. 22) |
|
Reported by Germany in 2005; without DTA since 2006 |
(credit given only on a reciprocal basis) |
|
United States |
No DTA |
(reciprocal tax credit only, same as in Germany, but only for federal income tax) |
Readers looking at this table should keep two things in mind. First: DTA and reciprocal treatment are not the same thing. Without a DTA, taxpayers rely on domestic rules for tax credits on taxes paid abroad—which are weaker, lack a tie-breaker, and have no negotiated limit. Second: the treaty method matters. The exemption method is the strongest shield—Brazil has relinquished jurisdiction. The credit method is a thinner shield—Brazil taxes first, but promises to deduct the amount of foreign tax from the tax due in Brazil.
Under Law 15.270/2025, this distinction is key. Foreign income covered by a specific DTA exemption (Joana) falls outside Brazilian tax jurisdiction and is therefore not included in the Minimum IRPF tax base. Income that generally falls under the exclusive jurisdiction of another state under the DTA (André, pilot’s salary) is also excluded, provided that compliance with the requirements can be proven. Income subject to a tax credit under the DTA is the territory where the Minimum IRPF may, in theory, be applied, but with the foreign tax credit.
Non-residents and “bad debt” from dividends
So far, the focus has been on Brazilian residents with foreign income. There is a mirror image of this problem on the other side of the ocean: non-residents who receive dividends from Brazil. Law 15270/2025 changes their situation, and the practical risk is that they end up with a receivable that exists on paper but is never actually realized.
Starting in 2026, any dividend remitted abroad to a non-resident will be subject to a 10% withholding tax, with no minimum threshold. The R$50,000/month limit, which protects small resident shareholders, does not apply to non-residents. If pilot André finalizes his permanent departure — and understands how non-resident taxation works in Brazil—he will be subject to a 10% tax on each dividend, including those from shares he holds on the Brazilian stock exchange.
The law provides for a reduction to prevent an excessive tax burden: when the sum of IRPJ + CSLL (at the corporate level) + 10% IRRF (on the partner) exceeds the nominal IRPJ + CSLL rates for the corporation (34% for general businesses, 40% for insurers/financial institutions, 45% for banks), the partner is entitled to recover the difference. The problem for non-residents is that the law merely states that the Federal Revenue Service will issue regulations on how non-residents can recover this amount.
The procedures for claiming a tax refund have not been established
A request for the recovery of the overpayment—as a credit rather than a refund—must be made within 360 days of the distribution. However, the law does not clarify:
- Which system should we use? PER/DCOMP? A new administrative request? The IRS has not issued a specific circular.
- What documents do I need to submit? Is the DARF for the withholding tax sufficient? Is proof of residence required?
- Offset against what? Non-residents typically have no other federal tax liabilities in Brazil—the logic behind the PER/DCOMP is virtually inapplicable, and the law does not provide for a cash refund.
- When will I receive the refund? Tax refunds for non-residents are typically slow and bureaucratic, especially if the non-resident does not have a CNR account in Brazil.
In practice, a non-resident partner in a Brazilian holding company—or one with capital invested in publicly traded shares—runs the risk of having funds withheld without ever being able to recover the excess amount paid. In other words, it is a bad debt: a right that exists in theory but cannot be enforced in practice.
Double taxation treaties do not provide protection in this regard. All Brazilian double taxation treaties grant Brazil the authority to tax dividends up to a certain amount, typically 15%, or 10% in the most favorable cases. To my knowledge, none of them sets a limit lower than 10%.
This is, more than anything, a discussion about tax justice. If the IRS is required to refund the excess amount withheld, the taxpayer may seek a court order to ensure that the refund mechanism chosen by the tax authorities is effectively implemented. Those most affected are Brazilians who have left the country permanently, retained ownership interests in Brazil, and rely on dividends to support their household budgets abroad.
What can you do in 2026?
The law has been passed; the minimum income tax threshold took effect on January 1, 2026, and the first tax return is due in 2027. What is the best course of action now, given your financial situation?
Profile |
Priorities for 2026 |
|---|---|
Resident in Brazil with foreign income (Joana) |
(1) Document how income is treated in the source country and the applicable treaty method; (2) calculate the minimum income tax under two scenarios (with and without the income covered by the treaty); (3) assess whether to file a preventive writ of mandamus before the 2027 tax return if the amount in question justifies it, or accept the cost of inaction. |
Brazilian player abroad without a formalized permanent transfer (André) |
(1) Seriously consider declaring permanent departure from the country—as a general rule, this resolves the issue of dual residency at its root; (2) if you choose to maintain the current situation, compile robust documentation of residency abroad (certificate of tax residency, proof of address, family ties, income tax return filed in the foreign country); (3) Otherwise, assess whether waiving the non-taxation status and seeking to utilize the foreign tax credit would be the most favorable solution. |
Non-resident with an equity interest in Brazil |
(1) Review the structure—is it worth keeping the foreign PF directly within the Brazilian PJ, or should a real estate holding company be set up as an intermediary PJ to obtain a tax deferral (since dividends from one PJ to another within Brazil are not taxed)? (2) Monitor the regulations governing the refund process for excess IRRF. |
Three rules apply to all profiles.
First: don’t act hastily. Many details still depend on regulations (the specific IN for the Minimum Personal Income Tax, the mechanism for recovering excess payments, and how it interacts with the DTA). Structural decisions—such as setting up a holding company or making a permanent exit—should be based on the text of the law, not on Instagram rumors.
Second: documentation is key. In international taxation, the taxpayer wins when they have the paperwork: a certificate of tax residence, a certified translation, a foreign income tax return, and proof of taxes paid abroad. Without documentation, there is no case—no matter how solid the argument may be.
Third: the cost of defending this right is real. The argument based on Article 98 of the CTN is strong, but defending it requires preparation and a willingness to go to court. Whether this is worth it or not depends on the context.
Conclusion
Law 15270/2025 has a justifiable primary objective: to tax at least a minimum amount from those who, until 2025, paid very little thanks to the dividend exemption. The design, however, has created an extremely complex system, riddled with legal loopholes, and in unnecessary conflict with treaties that Brazil has committed to respect. By including “all income” in the Minimum IRPF base in a non-technical manner, the wording of the law encompasses income protected by DTA.
For those with dual residency or significant foreign income, the message for 2026 is clear. The DTA is Vogel’s interpretation of the new law: it does not create a tax, nor does it repeal Brazilian law, but it prevents its application in the cases it covers. Law 15.270/2025 encounters a barrier that was already in place in 1974 (Spain), 1978 (Italy), 1967 (Japan), and 2001 (Portugal)—and, under Article 98 of the CTN, it cannot remove it.
For those who want to be well prepared by 2026, here’s what needs to be done: understand the program, gather the necessary documentation, calculate your budget with and without the income protection, and decide how to proceed.
Neste blog você encontrará sempre informações relevantes e atualizadas a respeito do tema, e orientações para evitar problemas com o Fisco e demais autoridades. Fique à vontade para nos relatar sua experiência, compartilhar o conteúdo com outros amigos que necessitem de orientações e entrar em contato conosco através do e-mail [email protected] ou então via WhatsApp. Clique aqui para enviar uma mensagem agora.
Conte comigo!
Warm regards,
Vinicius Tersi
Referências:
- 1See Law No. 9,249/1995, Art. 6-A, as amended by Law No. 15270/2025.
- 2See Law No. 9,249/1995, Art. 16-A, also included in Law No. 15270/2025.
- 3Law 15270/2025 makes no direct reference to the offset of tax paid abroad, but to Article 12 of Law 9,250/1995, which states in subsection VI that the annual income tax due at progressive rates may be reduced by offsetting tax paid abroad, provided there is reciprocal treatment (the procedure in the absence of a treaty). It also refers to Law No. 14,754/2023, which addresses the offset of tax credits when there is a double taxation agreement (DTA) or, in its absence, reciprocal treatment. Since domestic law does not address exemptions, but Law 15270/2025 explicitly states that exempt income is included in the calculation basis for the Minimum Personal Income Tax (IRPF Mínimo), this gap remains.
- 4The concept of tax residence under Italian law is set forth in CIR/85, Art. 2, and the Testo Unico.
Homepage – English › Forums › Law 15270 and Income Earned Abroad: Does the Treaty Still Provide Protection?